How bulk commodities pricing affects long-term supply contracts
Long-term supply contracts do not remove commodity price risk; they determine who carries it, when it is recognized, and whether it can be managed before it damages margin or continuity of supply. That distinction is central when contracting for bulk commodities such as metals, ores, agricultural feedstocks, chemicals, coal, industrial minerals, pulp, polymers, or other high-volume inputs.
A contract that appears to offer price certainty can still create substantial exposure if the pricing basis, adjustment timing, freight treatment, quality terms, or volume commitments do not match the buyer’s actual cost and revenue cycle. Conversely, a contract linked to a transparent market index may be more volatile on paper but economically safer because it follows the buyer’s downstream selling prices or permits timely hedging.
The practical question is not whether a fixed or floating price is better. It is whether the contract converts a volatile market into a cost structure the business can absorb, forecast, and control.
Commodity prices affect more than the unit price
For bulk commodities, the agreed price is normally only one layer of the delivered-cost equation. A multi-year supply arrangement may also be affected by freight, fuel, port charges, inland transportation, storage, insurance, duties, exchange rates, financing costs, quality differentials, carbon-related costs, and disruption-related surcharges. A contract that fixes only the commodity reference price can leave most of the commercial exposure open.
This is especially important where the material itself accounts for a large share of the finished product’s cost. In such cases, a relatively small movement in the underlying commodity can have a disproportionate effect on gross margin, working capital needs, and inventory valuation. Where the material is less significant in the finished product, the primary concern may instead be supply availability, delivery reliability, or the cost of production interruption.
Business evaluation should therefore begin with a cost waterfall rather than the supplier’s quoted price:
- the market reference price for the commodity;
- the supplier’s conversion, processing, or handling premium;
- quality, grade, origin, and packaging differentials;
- ocean, rail, road, pipeline, or barge freight;
- port, terminal, warehousing, and demurrage exposure;
- currency conversion and payment-term effects;
- tariffs, taxes, duties, and compliance-related charges; and
- inventory carrying cost from shipment to consumption.
Each element may respond to different market forces. A metal benchmark can fall while regional physical premiums rise because local supply is constrained. Grain prices may soften while export freight rises because vessel availability tightens. An energy-intensive chemical feedstock may decline while the supplier’s conversion charge increases due to utility or labor costs. Treating these components as one undifferentiated price obscures where the real risk sits.
Fixed pricing is a risk transfer, not automatically a saving
A fixed-price contract gives a known price for an agreed period, often in exchange for a volume commitment or a supplier commitment to reserve capacity. It can support budgeting, bid pricing, and margin planning when the buyer’s sales prices are also fixed or when production schedules cannot tolerate interruptions.
Its weakness is basis mismatch: the buyer locks an input cost at one point in the cycle while its own revenue may continue to move with the market. If market prices subsequently decline, the buyer may be committed to an above-market input cost. That outcome is not necessarily evidence of a poor decision. It becomes a problem when the contract has not been evaluated as an insurance cost and there is no commercial reason to maintain that protection.
Fixed prices are most defensible when the buyer has a clear exposure that needs to be stabilized. Examples include a fixed-price customer project, a regulated selling price, a production process with limited ability to substitute materials, or a market in which physical availability is considered more damaging than price upside.
Even then, a single fixed price for the entire contract term can be unnecessarily rigid. Parties may use fixed-price periods with scheduled reopeners, fixed prices for a committed base volume and indexed pricing for additional volume, or layered purchases at different dates. These structures do not eliminate volatility, but they avoid making one market observation determine the economics of several years of supply.
Index-linked pricing works only when the index reflects the physical market
Indexation is widely used because it creates a visible connection between the contract price and an external market reference. A typical formula may link the price to a published benchmark, plus or minus a negotiated premium:
Delivered contract price = reference index + physical premium + freight component + agreed adjustments
The simplicity of this formula can be misleading. Its effectiveness depends on the index being relevant to the material actually delivered. A benchmark may represent a different geography, grade, delivery point, currency, or timing convention from the physical commodity purchased. The resulting difference is known broadly as basis risk.
Consider an imported bulk material priced against an international benchmark. The benchmark may capture global commodity movement, but it may not reflect congestion at the destination port, a shortage of region-specific grade, local regulatory restrictions, or a widening premium for immediate delivery. If those gaps are not addressed, the buyer remains exposed even though the contract is “indexed.”
A sound pricing clause identifies more than the index name. It should specify:
- the publication and exact assessment or settlement series;
- the quotation currency and unit of measure;
- the averaging period;
- the pricing date in relation to shipment, bill of lading, arrival, or delivery;
- the grade, specification, or conversion factor used;
- the treatment of non-published days, corrections, or discontinued assessments; and
- the replacement method if the original benchmark becomes unavailable or materially changes.
Ambiguity in these provisions can become expensive when the market moves sharply. A clause that says “market price at delivery” without defining the reference, timing, and delivery point does not create flexibility; it creates room for dispute.
Timing rules can matter as much as the benchmark itself
Commodity price exposure is shaped by the gap between the date when price is set and the date when the material is consumed, resold, or incorporated into a finished product. This gap is often overlooked in negotiations because the parties focus on the benchmark rather than on the pricing window.
Pricing at shipment may suit a supplier whose costs and hedging are tied to loading. Pricing at arrival may better suit a buyer that faces destination-market risk. Monthly average pricing can smooth daily movements, but it can also create uncertainty during the month and may not align with a buyer’s customer contracts. A lagged monthly average may make invoicing easier, yet it can leave either party exposed if physical costs move before the formula catches up.
The right approach depends on operational reality. If transit takes several weeks, a shipment-date price may be commercially different from an arrival-date price even when the same index is used. If consumption is continuous, an average-based formula may align well with actual usage. If material is bought for a specific project with a known delivery date, a fixed or date-specific price may be more appropriate.
Price timing also affects hedge effectiveness. Financial hedges, where available, tend to settle against defined market dates and benchmarks. A physical contract with a vague or unusual pricing period can be difficult to offset. The business may believe it is protected because it has both a supply agreement and a hedge, while the timing mismatch leaves a residual exposure that only becomes visible in reconciliation.
Freight and logistics can overturn the original contract economics
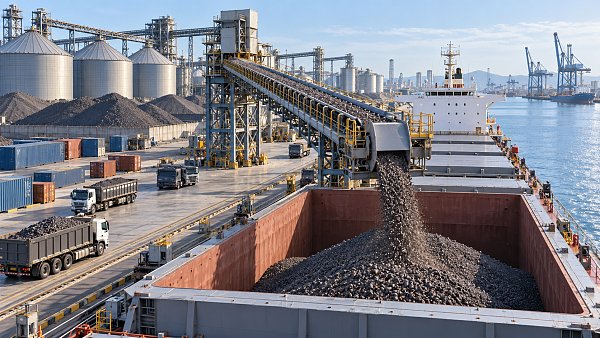
Bulk commodities are unusually sensitive to logistics because freight is often a material part of delivered cost and because transport capacity cannot always be secured at the same time as the commodity. A long-term agreement may lock in product availability but leave the buyer exposed to spot freight, or it may include freight at a level that no longer reflects the operating environment.
The commercial effect depends on the delivery term. Under an origin-based arrangement, the buyer may bear the cost and execution risk of ocean freight, insurance, port handling, and onward transport. Under a delivered arrangement, more of that risk may sit with the supplier, but the supplier will usually price that risk into the offer or seek a freight adjustment mechanism.
Freight provisions need the same discipline as commodity index clauses. The contract should state whether freight is fixed, indexed, capped, passed through at cost, or subject to a defined escalation formula. It should also clarify which party bears costs arising from waiting time, port restrictions, changes in vessel size, route diversions, and storage caused by late document release or inspection delays.
There is no universally favorable allocation. A buyer with strong logistics capability and diversified carrier access may prefer to control transport. A buyer with smaller volumes or limited port experience may place greater value on a delivered price, even if that price includes a risk premium. The decision should reflect control over the risk, not only the visible freight charge.
Volume commitments turn price clauses into operational commitments
Long-term supply contracts often exchange price treatment for volume certainty. The supplier may offer a lower premium, reserved capacity, or priority allocation in return for annual minimum purchases, take-or-pay provisions, or narrow tolerance bands. These commitments can be valuable when supply security is essential, but they can become costly when demand falls, specifications change, or the buyer’s production mix shifts.
Contracted volume should be tested against realistic consumption ranges rather than a single forecast. A useful distinction is between:
- firm volume, needed to protect core production;
- flexible volume, which may be adjusted within agreed notice periods; and
- contingent volume, available under an option, allocation, or call-off mechanism.
Without this separation, a buyer may pay for supply certainty on demand that was never sufficiently certain. At the same time, excessive flexibility can reduce supplier willingness to hold inventory or capacity. The commercial balance is usually stronger when the supplier receives a credible base-load commitment and the buyer retains controlled flexibility around it.
Minimum-volume obligations should not be assessed only as a purchase requirement. They should be examined alongside quality acceptance rights, delivery performance, force majeure provisions, substitution rights, and the consequences of repeated non-conforming deliveries. A buyer should not be obligated to take volume without a workable remedy when the delivered material cannot be used in the intended process.
Quality and yield can be hidden pricing variables
For bulk commodities, nominal price comparisons can be misleading if grades differ in usable content, moisture, impurity levels, calorific value, particle size, contamination, or processing yield. A lower-priced cargo may be more expensive after adjustment for reject rates, energy consumption, waste disposal, lost throughput, or blending requirements.
Long-term agreements should make quality economics measurable. Specifications need to define the accepted range, sampling method, testing laboratory or dispute procedure, and commercial consequences of off-spec material. A clear schedule of penalties and premiums can be preferable to a simple rejection right because it allows parties to calculate the value of a deviation and decide whether the cargo remains usable.
Measurement is particularly important when invoices depend on net weight, dry metric tonnes, contained metal, active ingredient, or energy content. Differences between loading-port and discharge-port measurement methods can lead to repeated reconciliation disputes. The governing measurement point and the right to independent testing should be established before the first shipment, not after a disputed cargo arrives.
Currency, credit, and inventory exposure are part of the price decision
A commodity may be priced in a currency different from the buyer’s reporting currency or customer revenue currency. This creates a second source of volatility that may offset or amplify the commodity movement. A falling dollar-denominated benchmark does not necessarily lower local-currency cost if the local currency weakens at the same time.
Payment terms also change the economic cost. A supplier offering a lower nominal price but requiring payment before shipment may impose a larger working-capital burden than a slightly higher-priced supplier offering credit aligned with the buyer’s sales cycle. For cargoes with long transit times, financing cost and inventory exposure can be significant even without a change in the quoted commodity price.
The relevant comparison is therefore landed and financed cost at the point of use, not simply invoice value. This is where contract evaluation benefits from scenario analysis: testing combined changes in commodity price, freight, currency, volume utilization, and payment timing rather than varying one input at a time.
Price review clauses need boundaries
Long-term contracts frequently include renegotiation or hardship language intended to address exceptional changes in market conditions. Such clauses can preserve relationships, but vague wording may undermine the certainty the contract was meant to provide.
A usable review mechanism defines the trigger, evidence required, negotiation period, interim pricing treatment, and outcome if agreement cannot be reached. A trigger might relate to a specified change in an identified cost component, a sustained disruption to an agreed benchmark, or a regulatory measure that directly affects supply performance. Broad references to “material market change” invite disagreement because parties can differ on what is material and whether the change was already part of normal commodity risk.
Review rights should not become a substitute for clear original pricing. If freight, energy, carbon cost, exchange rate, or duties are foreseeable components of delivered cost, they should be addressed directly through the formula or allocation of risk. Renegotiation clauses are better reserved for events the formula cannot reasonably accommodate.
What a resilient long-term pricing arrangement looks like
A resilient contract does not attempt to predict the next commodity cycle. It makes exposure visible and assigns it to the party best able to manage it. It distinguishes the market price from physical premiums, logistics cost, quality value, currency exposure, and financing effects. It also provides workable procedures when market references, transport conditions, or specifications no longer function as originally expected.
The strongest commercial outcome is rarely the lowest price quoted on signing day. It is the arrangement whose economics remain understandable when prices diverge from forecasts, freight conditions change, volume demand shifts, or a shipment is delayed. In bulk commodities procurement, durability comes from precision: a defined benchmark, an appropriate timing rule, realistic volume flexibility, measurable quality terms, and a delivered-cost view that extends beyond the commodity headline price.
 When dual sourcing makes sense in a sourcing strategy for manufacturersSourcing strategy for manufacturers: learn when dual sourcing strengthens supply continuity, reduces disruption risk, and protects production without adding unnecessary complexity.
 How bulk commodities pricing affects long-term supply contractsBulk commodities pricing shapes long-term supply contracts through index rules, freight, quality, volume, and currency risk. Explore strategies for resilient costs and supply security.
 Which global manufacturing trends by sector matter most for sourcing plans?Global manufacturing trends by sector: identify sourcing risks, supplier resilience, compliance demands, and cost drivers to build smarter, more reliable procurement plans.
 What industrial trade intelligence pricing should include before you subscribeIndustrial trade intelligence pricing explained: compare coverage, data quality, access rights, and workflow value before choosing a subscription that supports smarter trade decisions.
 How an industrial trade intelligence dashboard can identify new supplier marketsDiscover how an industrial trade intelligence dashboard helps identify new supplier markets by comparing capacity, landed cost, logistics resilience, and compliance risk.
 Which global market entry barriers should exporters assess first?Global market entry barriers exporters should assess first: tariffs, compliance, buyer qualification, logistics, and payment risk. Build a practical strategy for confident market entry.
 How trade data aggregation analytics can reveal emerging supplier marketsTrade data aggregation analytics reveals emerging supplier markets by connecting trade flows, capacity signals, logistics, and compliance insights for smarter sourcing decisions.
 When an export market analysis platform can validate demand in a new marketExport market analysis platform insights help validate new-market demand through buyer fit, regulations, logistics, competition, and profitable entry conditions.
 What is driving the beauty and personal care market in the USA?Beauty and personal care in USA is driven by targeted solutions, selective premiumization, digital discovery, clean-label trust, diverse needs, and compliance. Explore key growth opportunities.
 How trade flow monitoring reports reveal changing regional demandTrade flow monitoring reports reveal changing regional demand through import volumes, sourcing shifts, product mix, logistics signals, and regulatory trends. Explore actionable market insights.
 How international market intelligence for investors reduces market-entry riskInternational market intelligence for investors reduces market-entry risk by validating demand, regulations, logistics, and competition before capital is committed.
 How international sourcing intelligence helps identify supplier risk earlyInternational sourcing intelligence helps businesses spot supplier risks early, protect supply continuity, and make smarter global procurement decisions.
 How trade data aggregation analytics reveals emerging supplier marketsTrade data aggregation analytics reveals emerging supplier markets through export trends, input flows, logistics, and regulatory signals. Discover smarter sourcing insights.
 What industrial cluster monitoring in Vietnam reveals about site riskIndustrial cluster monitoring Vietnam reveals hidden site risks across labor, utilities, logistics, compliance, and supplier dependencies. Make smarter sourcing and expansion decisions.
 Food Technology Trends Reshaping Shelf Life, Safety, and Product InnovationFood technology is reshaping shelf life, safety, and innovation. Discover the trends helping food businesses cut risk, improve compliance, and unlock stronger global market growth.
 How electronics manufacturing services are changing with low-volume demandElectronics manufacturing services are evolving fast with low-volume demand. Learn how agile EMS partners improve flexibility, compliance, sourcing resilience, and speed to market.
 How Can Buyers Reduce Procurement Risks for Electronic Components?How to reduce procurement risks for electronic components: learn how buyers assess traceability, lead times, compliance, and supplier types to avoid costly sourcing mistakes.
 What Sourcing Intelligence India Reveals About Supplier Risk and Cost ShiftsSourcing intelligence India reveals hidden supplier risk, compliance gaps, logistics pressure, and real cost shifts—helping buyers compare vendors smarter and source with more confidence.
 Fashion Trends 2026: Which Materials, Colors, and Silhouettes Are Gaining Ground?Fashion trends 2026 spotlight tactile fabrics, mineral colors, and controlled volume. Explore the materials, shades, and silhouettes shaping smarter, more wearable style.
 Smart Device Market Outlook: Key Growth Drivers, Segments, and Business OpportunitiesSmart device market trends are shifting toward system value, industrial demand, and resilient supply chains. Explore key growth drivers, high-potential segments, and business opportunities.
 How Global Trade Intelligence Services Help B2B Firms Evaluate Markets and SuppliersGlobal trade intelligence services help B2B firms compare suppliers, assess market potential, and uncover compliance, logistics, and pricing risks before costly decisions are made.
Global Trade Insights & Industry
Our mission is to empower global exporters and importers with data-driven insights that foster strategic growth.
Search News
Popular Tags
Industry Overview
The global commercial kitchen equipment market is projected to reach $112 billion by 2027. Driven by urbanization, the rise of e-commerce food delivery, and strict hygiene regulations.