How an industrial trade intelligence dashboard can identify new supplier markets
New supplier markets are rarely visible through a single signal. A region can show rising exports while local factories are already operating near capacity. Another can offer attractive unit prices but face port congestion, uncertain input availability, or product rules that create expensive rework after the first shipment. An industrial trade intelligence dashboard brings these signals into one working view, making it possible to compare supplier markets as operating environments rather than as country names on a shortlist.
The useful output is not a generic ranking. It is a reasoned view of where a product category can be sourced with an acceptable combination of capability, continuity, landed cost, and compliance exposure. That distinction matters when supply is being evaluated across machinery parts, electronics, chemical materials, building products, medical components, food packaging, consumer goods, or other categories with different production and transport constraints.
Start with market evidence, not a supplier directory
A directory can show that factories exist in a location. It does not establish whether that location is becoming a viable supply market for a particular product. A dashboard should first reveal the direction and composition of trade activity: which product groups are leaving a region, which destination markets are receiving them, whether the mix is shifting toward finished goods or intermediate inputs, and whether shipments are broad-based or concentrated among a few exporters.
Export growth needs interpretation. Rising outbound volume for stamped metal components, for example, may indicate expanding local tooling, press capacity, finishing capability, and a supporting fastener or coating ecosystem. It could also reflect temporary diversion from another origin after a disruption. The first pattern may support a durable sourcing option; the second may disappear once the original trade route normalizes. Shipment history, destination diversification, related material flows, and production-investment signals help separate those explanations.
Product classification alone also has limits. Two products within the same customs category can have materially different sourcing requirements. A cast valve body, a machined stainless-steel valve, and a fully assembled control valve may appear close in trade records but rely on different foundry practices, machining tolerances, seal materials, testing equipment, and documentation. The market view becomes meaningful only after trade data is connected to the actual bill of materials and manufacturing route.
Translate demand movement into supplier-market potential
Demand in an import market can point to a new source region before supplier awareness catches up. If imports of a category are increasing while established origins show longer lead times, rising input costs, or constrained shipping capacity, adjacent manufacturing regions deserve closer examination. The relevant question is not simply whether imports are growing. It is whether the demand pattern matches capabilities that the alternative region can realistically support.
Consider a product requiring injection-molded housings, copper terminals, assembly labor, electrical testing, and export-grade packaging. A region with strong plastics conversion but limited electrical-component production may be suitable for simple enclosures, yet less suitable for a finished electrical assembly. Import demand can still be useful evidence, but it should direct the evaluation toward the proper level of production: raw material, part manufacture, subassembly, or completed product.
Demand quality matters as much as demand direction. Replenishment demand for standardized hardware behaves differently from project demand for pumps, solar mounting systems, laboratory equipment, or prefabricated building components. Project orders may be larger but intermittent, with technical approvals, site installation schedules, and spare-parts obligations affecting supplier selection. A market that looks attractive on shipment value may be too dependent on irregular projects to support stable production planning.
Signals that deserve to be read together
- Trade flow and destination mix: exports reaching several demanding destinations suggest a broader commercial base than shipments concentrated in one nearby market or one intermediary hub.
- Related input availability: imports of resin, specialty steel, electronic components, packaging materials, or active ingredients can reveal whether local production depends on fragile external supply.
- Manufacturing depth: assembly capacity is different from control over tooling, surface treatment, precision machining, calibration, or final testing.
- Buyer requirement changes: new traceability, labeling, safety, environmental, or documentation expectations can alter the practical value of a low-cost origin.
These signals should not be collapsed into a single score too early. A lower-cost market with external dependence on one critical component has a different risk profile from a higher-cost market with local material conversion and redundant freight options. Both may remain viable, but they suit different sourcing strategies.
Measure production capacity in the form that affects delivery
Headline industrial output is often too broad to predict whether a supplier market can absorb a new order. Capacity has to be examined at the process level. For fabricated metal products, the constraint may be laser cutting, bending, galvanizing, powder coating, welding fixtures, or final inspection. For electronics, the limiting stage could be PCB fabrication, SMT placement, component allocation, functional testing, conformal coating, or export packing. For food and agricultural products, cold storage, cleaning, grading, hygienic processing, and temperature-controlled dispatch may matter more than nominal factory count.
Capacity also changes with order characteristics. A factory network that handles high-volume, repeatable SKUs efficiently may struggle with low-volume variants that require frequent tool changes, custom labeling, mixed-material assembly, or small-batch quality documentation. Conversely, a market with flexible workshops may be a poor fit for a program requiring automated consistency across long production runs. The dashboard should allow the market question to be framed around product complexity, batch size, tolerance sensitivity, and expected replenishment pattern.
Seasonality deserves equal attention. Agricultural processing, commodity-derived chemicals, textiles, construction materials, and certain consumer categories can have production peaks linked to harvests, weather, holiday demand, or local project cycles. A region may appear to have spare capacity in annual figures while being unavailable during the months that matter for a launch or maintenance shutdown. Monthly trade movement, freight pressure, and local operating patterns provide a better planning basis than an annual average.
Separate price competitiveness from landed-cost resilience
A market can appear inexpensive at the factory gate yet become less competitive once inland transport, container availability, transshipment, insurance exposure, customs treatment, packaging changes, inspection needs, and inventory carrying time are considered. A trade intelligence view should expose these cost drivers without pretending they are fixed. Freight conditions can shift quickly, and the significance of a shipping route varies according to product density, hazard classification, shelf life, and order frequency.
Heavy castings and building materials are particularly sensitive to freight and handling. Low-value, high-weight goods can lose their apparent price advantage when moving over long inland distances before export. High-value electronic modules may absorb higher freight more easily, but they can be exposed to damage, moisture, electrostatic handling requirements, theft risk, or time-sensitive component allocation. Chemical products introduce another layer: packaging type, compatibility, dangerous-goods handling, and storage conditions can narrow the realistic set of routes and warehouses.
Comparing total landed cost also requires an honest view of working capital. A distant origin with a low product price may require earlier order commitment and greater buffer stock. That can be acceptable for stable, standardized items. It is less attractive when specifications change frequently, demand is volatile, or model revisions can leave inventory obsolete.
Use regulatory signals as a market filter, not a final paperwork task
Regulatory developments can change the attractiveness of a supplier market before any specific supplier is contacted. The issue is not limited to whether a product is legally permitted to enter a destination. Requirements can affect substance declarations, product marking, labeling language, material traceability, hygiene controls, energy performance, packaging composition, technical files, origin evidence, or documentation held by upstream component producers.
These obligations land differently across supply chains. A simple metal bracket may need material traceability and corrosion-performance evidence, while an electrical cabinet can require component-level records, wiring documentation, testing evidence, and consistent labeling. Medical, food-contact, chemical, and child-related products often require closer control of inputs and production records. A region with low prices but weak documentation discipline can create repeated engineering and quality work that is invisible in an initial quotation.
Tariff treatment must likewise be tied to origin rules and actual production steps. Final assembly in a market does not always establish the origin outcome assumed in a pricing model. Where key materials, components, or transformation stages occur can affect customs treatment and supporting documents. This is why a dashboard is most useful when policy changes are connected to product categories, upstream sourcing patterns, and likely operational follow-up rather than displayed as isolated headlines.
Find the distinction between a new market and a new dependency
Supplier-market diversification can reduce exposure, but adding a second country does not automatically create independence. Two regions may rely on the same resin producer, wafer source, steel mill, shipping lane, tooling supplier, or component distributor. A disruption in that shared upstream node can affect both sources at once. Mapping material and component dependencies is especially important for electronics, engineered plastics, specialized alloys, batteries, industrial seals, and products with a small number of qualified inputs.
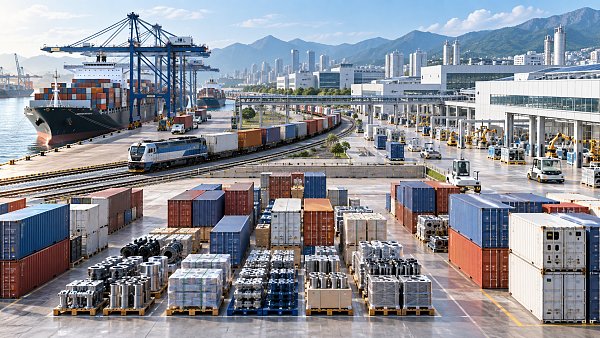
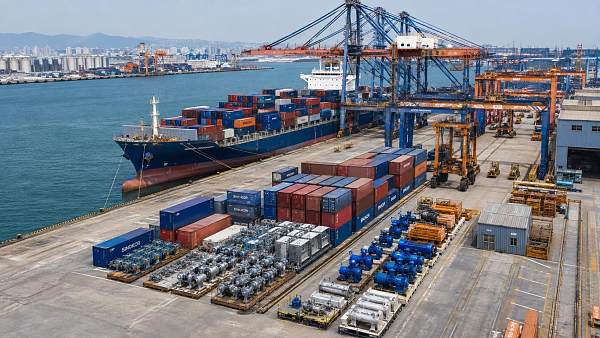
The same principle applies to logistics. Alternative ports are valuable only when inland links, booking access, warehouse capacity, and customs procedures can support the required service level. A route that works for containerized consumer goods may be unsuitable for oversized machinery, temperature-sensitive food products, or dangerous goods. Transport mode, package dimensions, loading method, and storage conditions should sit beside the trade figures when judging supplier-market resilience.
There is also a practical difference between geographic diversification and operational diversification. Sourcing identical parts from factories in separate countries is useful only when both can maintain the same drawing revision, approved material substitutions, test method, packaging standard, and change-notification process. Without that alignment, a second market may create engineering variation rather than continuity.
Turn dashboard findings into a staged market assessment
The first pass should narrow the field based on product-market fit, trade continuity, process depth, route feasibility, and foreseeable regulatory exposure. This is a screening exercise, not a supplier approval. Its purpose is to avoid spending technical and commercial effort in markets where the category economics or operating conditions are structurally weak.
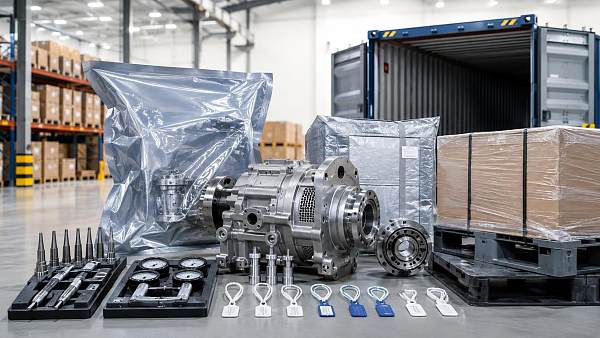
The next stage should test the assumptions behind the signal. A promising market can be examined through product-specific questions: Is the required material locally available in the needed grade? Does the production route require outsourced heat treatment, plating, sterilization, testing, or calibration? Are drawings and tolerances understood in the local supplier base? Can inspection records travel with the goods? Is the product protected adequately during the route being considered?
Only then does supplier-level verification become efficient. Sample quality, process controls, capacity commitments, traceability, corrective-action handling, tooling arrangements, and financial stability need direct review. The dashboard cannot replace that work. It improves the order in which the work is done by showing where the conditions for a credible supplier market are present.
A durable sourcing decision emerges when market evidence and operational evidence tell the same story. Strong exports without process depth are not enough. Low costs without route reliability are not enough. Broad industrial capability without the required documentation discipline is not enough. When trade flows, production conditions, input dependencies, logistics, and compliance requirements align around the actual product, a new supplier market becomes a defensible option rather than an attractive assumption.
- surface treatment
- laser cutting
- machinery parts
- electronic components
- building materials
- procurement
- testing equipment
- trade data
- trade intelligence
- supplier directory
- import market
- chemical materials
- product classification
- construction materials
- packaging materials
- industrial trade intelligence
- laboratory equipment
- food packaging
- consumer goods
- industrial trade intelligence dashboard
 How an industrial trade intelligence dashboard can identify new supplier marketsDiscover how an industrial trade intelligence dashboard helps identify new supplier markets by comparing capacity, landed cost, logistics resilience, and compliance risk.
 Which global market entry barriers should exporters assess first?Global market entry barriers exporters should assess first: tariffs, compliance, buyer qualification, logistics, and payment risk. Build a practical strategy for confident market entry.
 How trade data aggregation analytics can reveal emerging supplier marketsTrade data aggregation analytics reveals emerging supplier markets by connecting trade flows, capacity signals, logistics, and compliance insights for smarter sourcing decisions.
 When an export market analysis platform can validate demand in a new marketExport market analysis platform insights help validate new-market demand through buyer fit, regulations, logistics, competition, and profitable entry conditions.
 What is driving the beauty and personal care market in the USA?Beauty and personal care in USA is driven by targeted solutions, selective premiumization, digital discovery, clean-label trust, diverse needs, and compliance. Explore key growth opportunities.
 How trade flow monitoring reports reveal changing regional demandTrade flow monitoring reports reveal changing regional demand through import volumes, sourcing shifts, product mix, logistics signals, and regulatory trends. Explore actionable market insights.
 How international market intelligence for investors reduces market-entry riskInternational market intelligence for investors reduces market-entry risk by validating demand, regulations, logistics, and competition before capital is committed.
 How international sourcing intelligence helps identify supplier risk earlyInternational sourcing intelligence helps businesses spot supplier risks early, protect supply continuity, and make smarter global procurement decisions.
 How trade data aggregation analytics reveals emerging supplier marketsTrade data aggregation analytics reveals emerging supplier markets through export trends, input flows, logistics, and regulatory signals. Discover smarter sourcing insights.
 What industrial cluster monitoring in Vietnam reveals about site riskIndustrial cluster monitoring Vietnam reveals hidden site risks across labor, utilities, logistics, compliance, and supplier dependencies. Make smarter sourcing and expansion decisions.
 Food Technology Trends Reshaping Shelf Life, Safety, and Product InnovationFood technology is reshaping shelf life, safety, and innovation. Discover the trends helping food businesses cut risk, improve compliance, and unlock stronger global market growth.
 How electronics manufacturing services are changing with low-volume demandElectronics manufacturing services are evolving fast with low-volume demand. Learn how agile EMS partners improve flexibility, compliance, sourcing resilience, and speed to market.
 How Can Buyers Reduce Procurement Risks for Electronic Components?How to reduce procurement risks for electronic components: learn how buyers assess traceability, lead times, compliance, and supplier types to avoid costly sourcing mistakes.
 What Sourcing Intelligence India Reveals About Supplier Risk and Cost ShiftsSourcing intelligence India reveals hidden supplier risk, compliance gaps, logistics pressure, and real cost shifts—helping buyers compare vendors smarter and source with more confidence.
 Fashion Trends 2026: Which Materials, Colors, and Silhouettes Are Gaining Ground?Fashion trends 2026 spotlight tactile fabrics, mineral colors, and controlled volume. Explore the materials, shades, and silhouettes shaping smarter, more wearable style.
 Smart Device Market Outlook: Key Growth Drivers, Segments, and Business OpportunitiesSmart device market trends are shifting toward system value, industrial demand, and resilient supply chains. Explore key growth drivers, high-potential segments, and business opportunities.
 How Global Trade Intelligence Services Help B2B Firms Evaluate Markets and SuppliersGlobal trade intelligence services help B2B firms compare suppliers, assess market potential, and uncover compliance, logistics, and pricing risks before costly decisions are made.
 Manufacturing Sector Updates for Investors: What Signals Matter Most in 2025?Manufacturing sector updates for investors in 2025: track orders, margins, supply chains, regulation, and exports to spot resilient manufacturers and smarter investment signals.
 How Energy Market Intelligence Helps Businesses Track Price Risks and Demand ShiftsEnergy market intelligence helps businesses spot price risks, demand shifts, and supply pressure early—improving procurement, resilience, and faster strategic decisions.
 Precision Hardware Tools Market: Key Demand Drivers, Segments, and Growth OutlookPrecision hardware tools market trends are reshaping sourcing, compliance, and automation. Explore key demand drivers, segment shifts, regional supply patterns, and growth opportunities.
 How to Use Customs Import Data to Find Buyers, Track Competitors, and Spot Demand?Customs import data helps you find real buyers, track competitors, and spot demand shifts early. Learn practical ways to turn trade records into smarter global business decisions.
Global Trade Insights & Industry
Our mission is to empower global exporters and importers with data-driven insights that foster strategic growth.
Search News
Popular Tags
Industry Overview
The global commercial kitchen equipment market is projected to reach $112 billion by 2027. Driven by urbanization, the rise of e-commerce food delivery, and strict hygiene regulations.