Which global manufacturing trends by sector matter most for sourcing plans?
Which Global Manufacturing Trends by Sector Matter Most for Sourcing Plans?
Global manufacturing trends by sector are reshaping how business evaluators assess sourcing opportunities, supplier resilience, and long-term procurement risk across increasingly interconnected international supply chains.
For sourcing plans, the key question is not which sector is growing fastest. It is which changes can affect cost, continuity, compliance, quality, and supplier viability.
Business evaluators searching this topic usually need a practical framework for comparing sourcing regions, identifying material risks, and prioritizing sectors requiring closer supplier due diligence.
They are especially concerned with whether capacity is dependable, regulatory requirements are manageable, logistics remain stable, and suppliers can meet future technical or sustainability expectations.
The most useful analysis connects sector conditions with procurement decisions. It should translate market signals into actions involving supplier selection, contract design, inventory policy, and risk monitoring.
Start With the Signals That Directly Change Sourcing Decisions
Not every manufacturing trend deserves equal attention. Evaluators should focus first on trends that can alter total landed cost, supply continuity, compliance exposure, or customer acceptance.
Capacity shifts matter when production moves between countries, especially if suppliers depend on imported components, local incentives, concentrated labor pools, or limited specialized infrastructure.
Regulatory trends matter when a product requires certifications, traceability records, safety testing, environmental disclosures, or documentation before entering a target market.
Material volatility matters most in sectors with high exposure to metals, petrochemicals, energy inputs, agricultural commodities, rare earths, or specialized electronic materials.
Logistics trends deserve attention when sourcing depends on congested ports, fragile trade corridors, temperature-controlled transport, oversized cargo handling, or cross-border customs processing.
Technology adoption is also relevant because automation, digital quality controls, and advanced manufacturing systems can improve consistency while changing supplier cost structures.
Rather than tracking headlines, procurement teams should define measurable indicators for each category, including lead time variation, defect rates, certification status, freight exposure, and capacity utilization.
This approach makes global manufacturing trends by sector easier to compare because each trend is judged according to its commercial impact, not its visibility in industry news.
Industrial Machinery and Automation Require Capability-Based Evaluation
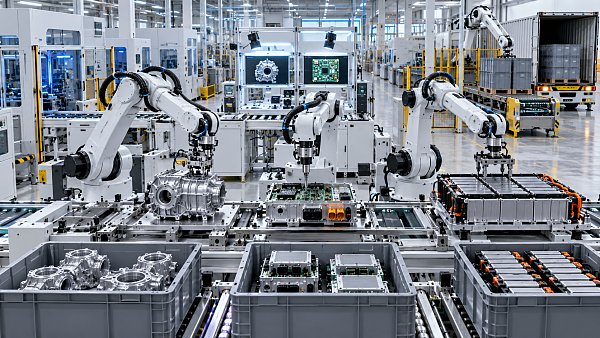
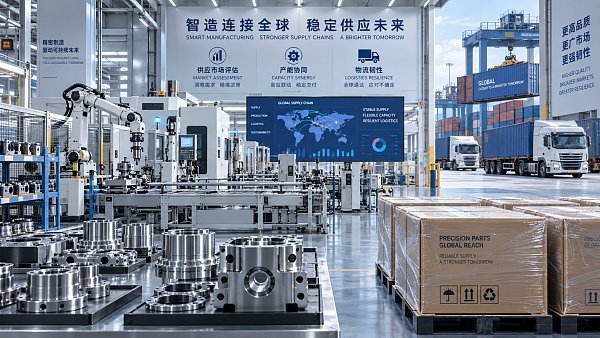
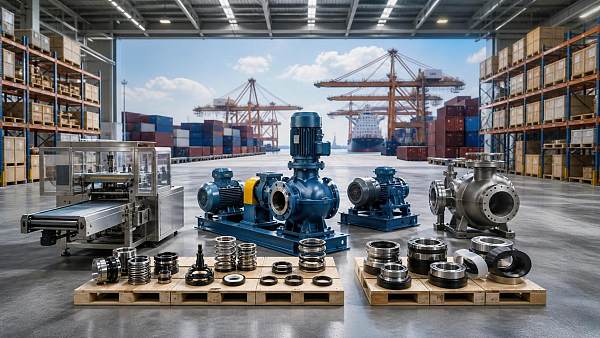
Machinery sourcing is increasingly shaped by automation, precision requirements, shorter equipment lifecycles, and demand for suppliers that can support customization, commissioning, and after-sales service.
For CNC equipment, industrial components, pumps, valves, bearings, fasteners, and molds, technical capability often matters more than the lowest unit quotation.
Evaluators should examine engineering depth, process control, calibration practices, tooling ownership, spare-parts availability, and the supplier’s ability to document product performance over time.
Automation is expanding in factories worldwide, but adoption levels vary widely. Suppliers using robotics and digital inspection may offer more stable quality and repeatable output.
However, automation alone does not prove reliability. Buyers should verify maintenance practices, operator expertise, production bottlenecks, and contingency plans for critical equipment failures.
Regionalization is another important trend. Buyers increasingly seek machinery suppliers closer to end markets to reduce installation delays, service costs, and replacement-part lead times.
For high-value capital equipment, assess the total ownership cost, including training, commissioning, software compatibility, warranty coverage, maintenance response, and expected operating efficiency.
A practical sourcing plan should maintain qualified alternatives for critical engineered parts, particularly where drawings, tooling, proprietary materials, or specialized certifications create switching barriers.
In this sector, the most valuable supplier is often the one that reduces operational interruption, rather than the supplier offering the lowest initial manufacturing price.
Electronics Sourcing Depends on Component Visibility and Supply Chain Depth
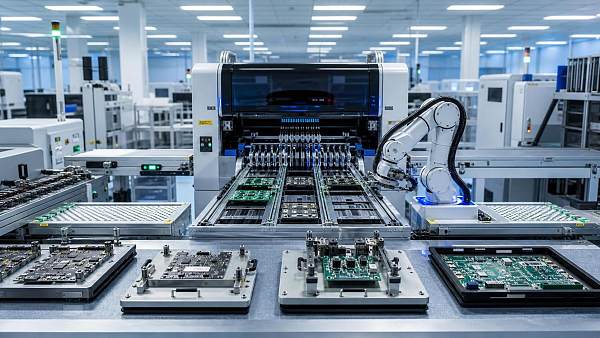
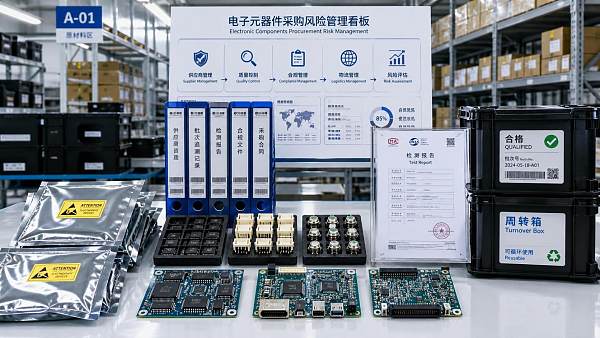
Electronics and electrical infrastructure remain highly exposed to semiconductor cycles, component allocation, technology transitions, export controls, and concentration in specialized manufacturing locations.
For sourcing teams, the central issue is rarely the finished product alone. It is the visibility of upstream components, including chips, PCBs, connectors, sensors, and passive devices.
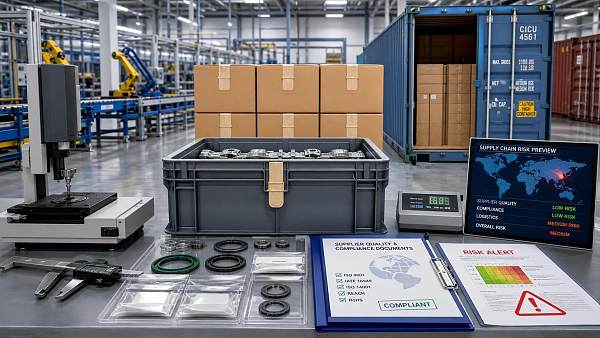
Suppliers should be evaluated on their approved vendor lists, component sourcing controls, counterfeit prevention methods, product lifecycle management, and ability to communicate end-of-life risks early.
Demand for electrification, data infrastructure, renewable power, and automation continues to support electrical equipment markets, while creating pressure on selected components and qualified materials.
Procurement teams should distinguish between standard components with broad substitution options and engineered parts requiring specific certifications, firmware, tooling, or safety approvals.
Electronics sourcing plans need stronger change-management controls. A component substitution can affect reliability, electromagnetic compatibility, safety approvals, and the customer’s final product qualification process.
Dual sourcing is useful only when alternatives are genuinely validated. Unqualified backup suppliers may create a false sense of resilience during shortages or sudden demand spikes.
Lead-time dashboards should track confirmed delivery performance, not only quoted lead times. Supplier promises may change quickly when upstream allocation or transport conditions deteriorate.
For business evaluators, the priority is establishing transparent multi-tier supply information before disruption occurs, rather than trying to reconstruct exposure after deliveries begin slipping.
Green Energy Manufacturing Brings Growth, Policy Exposure, and Traceability Demands
Green energy manufacturing is expanding across photovoltaics, batteries, grid equipment, energy storage, smart lighting, recycling systems, and environmental engineering technologies.
This growth creates sourcing opportunities, but it also increases exposure to policy changes, subsidy adjustments, trade remedies, localization rules, and rapidly evolving technical standards.
Solar and battery supply chains require particular attention because production capacity can expand quickly, while demand, tariffs, and local-content requirements change market economics abruptly.
Buyers should assess whether suppliers can document material origin, environmental performance, product testing, and compliance with destination-market requirements throughout the commercial relationship.
For batteries and energy storage systems, quality evaluation should include cell provenance, thermal management, battery management systems, safety testing, warranty terms, and recycling responsibilities.
Grid equipment sourcing requires a different lens. Interoperability, long product lifecycles, grid-code compliance, service capability, and spare-parts support can outweigh purchase-price differences.
Environmental claims also require scrutiny. Suppliers should provide evidence for recycled content, energy efficiency, emissions reporting, and certifications rather than relying on broad marketing statements.
Procurement leaders should avoid treating green manufacturing as one homogeneous category. Each product group has different bottlenecks, regulatory pressures, and performance failure consequences.
The strongest sourcing plans combine commercial competitiveness with documented compliance, technical validation, and clear fallback options for strategically important energy-related components.
Healthcare, Chemicals, and Food Need Compliance Before Cost Optimization
Healthcare, medical devices, chemicals, and food-related manufacturing are governed by stricter safety, traceability, hygiene, and documentation requirements than many general industrial categories.
In these sectors, a low-cost supplier can become expensive when incomplete records, inconsistent validation, contamination risks, or delayed regulatory approvals interrupt commercial activity.
Medical device sourcing should examine quality-management systems, traceability, sterilization controls, material biocompatibility, complaint handling, and post-market support responsibilities.
For laboratory equipment, consumables, and medical components, buyer evaluations should confirm whether design changes require notification, revalidation, customer approval, or new regulatory submissions.
Chemical and polymer sourcing requires attention to formulation consistency, restricted substances, safety data documentation, transport classification, storage requirements, and batch-level quality records.
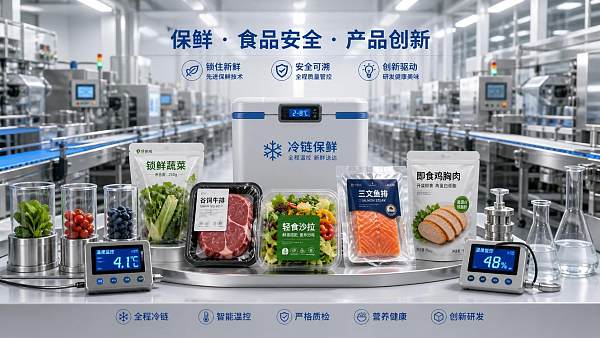
Food and agricultural supply chains face additional exposure to crop volatility, food safety rules, cold chain reliability, packaging compliance, and changing consumer expectations.
Suppliers in regulated sectors should be assessed through documented evidence, audits, sample testing, and corrective-action history rather than marketing materials or self-reported capabilities.
Business evaluators should also calculate the cost of noncompliance, including recalls, rejected shipments, product redesign, customer claims, legal exposure, and lost market access.
Here, sourcing resilience comes from disciplined qualification and change control. Price negotiations should follow compliance verification, not replace it as the primary decision tool.
Construction, Metals, and Materials Are Driven by Projects and Input Costs
Construction materials, steel, non-ferrous metals, mining equipment, and infrastructure products are strongly influenced by project cycles, energy costs, raw material availability, and regional standards.
These sectors often experience sharp pricing movement because commodity markets, infrastructure spending, currency changes, and trade restrictions can affect quotations within short planning periods.
When evaluating metal suppliers, buyers should separate base material pricing from fabrication capability, coating quality, dimensional control, certification, and delivery reliability.
Construction sourcing also depends heavily on local codes. A product accepted in one country may need different testing, fire ratings, seismic specifications, or environmental declarations elsewhere.
Prefabricated building systems are gaining attention because they can improve schedule predictability, reduce onsite labor needs, and simplify repeatable project delivery.
Yet prefabrication introduces its own risks, including transport dimensions, installation capability, local permitting, interface management, and dependency on accurate project engineering.
For project-based procurement, suppliers should be judged on production scheduling, packaging discipline, export experience, documentation accuracy, and capacity to handle phased deliveries.
Commodity risk can be managed through indexed pricing, defined validity periods, staged commitments, or contractual mechanisms that clarify how extraordinary material movements are addressed.
In these categories, the best decision usually balances technical compliance and project reliability with price protection, rather than pursuing fixed prices without supply assurances.
Consumer Goods Trends Make Speed, Transparency, and Flexibility More Important
Consumer goods manufacturing is shaped by shorter product cycles, changing retail demand, sustainability expectations, private-label growth, and pressure for faster replenishment.
Apparel, beauty, toys, home products, outdoor goods, gifts, and lifestyle categories require evaluators to consider both factory capability and commercial responsiveness.
A supplier may produce acceptable samples yet struggle with seasonal volume changes, color consistency, packaging requirements, social compliance, or timely shipment coordination.
For fashion and lifestyle products, material sourcing visibility is increasingly important because buyers may require recycled content, restricted-substance compliance, and ethical production evidence.
Consumer product sourcing should also test packaging quality, labeling accuracy, barcode readiness, retailer-specific requirements, and the supplier’s ability to manage product variations.
Nearshoring can improve speed for volatile demand, while established offshore production may remain advantageous for stable, high-volume products with predictable specifications.
Rather than applying one regional strategy to every item, buyers should segment portfolios by demand volatility, product complexity, margin sensitivity, and replenishment urgency.
Smaller trial orders can reveal practical supplier behavior before larger commitments. They provide evidence about communication quality, production discipline, inspection performance, and delivery accuracy.
For consumer categories, sourcing resilience is closely linked to operational flexibility: the ability to adjust quantities, manage variants, and protect brand quality under changing demand conditions.
Build a Sector-Based Sourcing Plan Instead of a Generic Risk Checklist
A useful sourcing plan translates global manufacturing trends by sector into a repeatable decision process that business evaluators can apply across categories and supplier regions.
First, classify purchases by business criticality. High-impact items require deeper supplier qualification, stronger contingency planning, and more frequent monitoring than routine indirect purchases.
Second, identify the sector-specific risk drivers. Electronics may require component visibility, while medical products need validation controls and construction materials need project-delivery assurance.
Third, compare suppliers using total landed cost. Include freight, tariffs, insurance, quality costs, inventory requirements, compliance administration, payment terms, and expected disruption exposure.
Fourth, assess resilience beyond supplier location. A nearby supplier can still be vulnerable if its materials, tooling, technical labor, or export approvals depend on concentrated external sources.
Fifth, create a monitoring rhythm that matches risk. Strategic categories may need monthly reviews of capacity, policy changes, freight conditions, commodity prices, and supplier performance.
Sixth, define escalation triggers before disruption occurs. Examples include repeated delivery variance, missing compliance documents, unusual price changes, declining quality metrics, or adverse regulatory developments.
Finally, ensure commercial teams, quality specialists, logistics providers, and finance stakeholders use the same supplier facts when making sourcing and investment decisions.
This cross-functional discipline turns market intelligence into operational readiness, helping organizations make earlier, more defensible decisions when sector conditions begin to change.
Conclusion: Focus on the Trends That Change Commercial Outcomes
The most important global manufacturing trends by sector are those that materially affect continuity, compliance, quality, delivery, cost, or the ability to serve customers reliably.
Industrial machinery rewards technical capability, electronics requires upstream transparency, green energy demands policy awareness, and regulated sectors require evidence-based supplier qualification.
Construction and materials sourcing depends on project execution and commodity exposure, while consumer goods planning requires flexibility, speed, and dependable product consistency.
Business evaluators should avoid broad assumptions about countries or industries. Better sourcing decisions come from linking sector-specific signals to defined commercial risks and measurable supplier performance.
By using a structured sector lens, procurement teams can identify where to diversify, where to validate more deeply, and where long-term supplier partnerships create genuine strategic value.
- smart lighting
- energy storage systems
- energy efficiency
- medical devices
- petrochemicals
- food safety
- cold chain
- procurement
- industrial machinery
- mining equipment
- market intelligence
- manufacturing trends
- supply chain
- global manufacturing trends
- electrical equipment
- green energy
- electrical infrastructure
- environmental engineering
- construction materials
- bearings
- non-ferrous metals
- laboratory equipment
- supplier due diligence
- packaging compliance
- consumer goods
- battery management systems
- global manufacturing trends by sector
 Which global manufacturing trends by sector matter most for sourcing plans?Global manufacturing trends by sector: identify sourcing risks, supplier resilience, compliance demands, and cost drivers to build smarter, more reliable procurement plans.
 What industrial trade intelligence pricing should include before you subscribeIndustrial trade intelligence pricing explained: compare coverage, data quality, access rights, and workflow value before choosing a subscription that supports smarter trade decisions.
 How an industrial trade intelligence dashboard can identify new supplier marketsDiscover how an industrial trade intelligence dashboard helps identify new supplier markets by comparing capacity, landed cost, logistics resilience, and compliance risk.
 Which global market entry barriers should exporters assess first?Global market entry barriers exporters should assess first: tariffs, compliance, buyer qualification, logistics, and payment risk. Build a practical strategy for confident market entry.
 How trade data aggregation analytics can reveal emerging supplier marketsTrade data aggregation analytics reveals emerging supplier markets by connecting trade flows, capacity signals, logistics, and compliance insights for smarter sourcing decisions.
 When an export market analysis platform can validate demand in a new marketExport market analysis platform insights help validate new-market demand through buyer fit, regulations, logistics, competition, and profitable entry conditions.
 What is driving the beauty and personal care market in the USA?Beauty and personal care in USA is driven by targeted solutions, selective premiumization, digital discovery, clean-label trust, diverse needs, and compliance. Explore key growth opportunities.
 How trade flow monitoring reports reveal changing regional demandTrade flow monitoring reports reveal changing regional demand through import volumes, sourcing shifts, product mix, logistics signals, and regulatory trends. Explore actionable market insights.
 How international market intelligence for investors reduces market-entry riskInternational market intelligence for investors reduces market-entry risk by validating demand, regulations, logistics, and competition before capital is committed.
 How international sourcing intelligence helps identify supplier risk earlyInternational sourcing intelligence helps businesses spot supplier risks early, protect supply continuity, and make smarter global procurement decisions.
 How trade data aggregation analytics reveals emerging supplier marketsTrade data aggregation analytics reveals emerging supplier markets through export trends, input flows, logistics, and regulatory signals. Discover smarter sourcing insights.
 What industrial cluster monitoring in Vietnam reveals about site riskIndustrial cluster monitoring Vietnam reveals hidden site risks across labor, utilities, logistics, compliance, and supplier dependencies. Make smarter sourcing and expansion decisions.
 Food Technology Trends Reshaping Shelf Life, Safety, and Product InnovationFood technology is reshaping shelf life, safety, and innovation. Discover the trends helping food businesses cut risk, improve compliance, and unlock stronger global market growth.
 How electronics manufacturing services are changing with low-volume demandElectronics manufacturing services are evolving fast with low-volume demand. Learn how agile EMS partners improve flexibility, compliance, sourcing resilience, and speed to market.
 How Can Buyers Reduce Procurement Risks for Electronic Components?How to reduce procurement risks for electronic components: learn how buyers assess traceability, lead times, compliance, and supplier types to avoid costly sourcing mistakes.
 What Sourcing Intelligence India Reveals About Supplier Risk and Cost ShiftsSourcing intelligence India reveals hidden supplier risk, compliance gaps, logistics pressure, and real cost shifts—helping buyers compare vendors smarter and source with more confidence.
 Fashion Trends 2026: Which Materials, Colors, and Silhouettes Are Gaining Ground?Fashion trends 2026 spotlight tactile fabrics, mineral colors, and controlled volume. Explore the materials, shades, and silhouettes shaping smarter, more wearable style.
 Smart Device Market Outlook: Key Growth Drivers, Segments, and Business OpportunitiesSmart device market trends are shifting toward system value, industrial demand, and resilient supply chains. Explore key growth drivers, high-potential segments, and business opportunities.
 How Global Trade Intelligence Services Help B2B Firms Evaluate Markets and SuppliersGlobal trade intelligence services help B2B firms compare suppliers, assess market potential, and uncover compliance, logistics, and pricing risks before costly decisions are made.
 Manufacturing Sector Updates for Investors: What Signals Matter Most in 2025?Manufacturing sector updates for investors in 2025: track orders, margins, supply chains, regulation, and exports to spot resilient manufacturers and smarter investment signals.
 How Energy Market Intelligence Helps Businesses Track Price Risks and Demand ShiftsEnergy market intelligence helps businesses spot price risks, demand shifts, and supply pressure early—improving procurement, resilience, and faster strategic decisions.
Global Trade Insights & Industry
Our mission is to empower global exporters and importers with data-driven insights that foster strategic growth.
Search News
Popular Tags
Industry Overview
The global commercial kitchen equipment market is projected to reach $112 billion by 2027. Driven by urbanization, the rise of e-commerce food delivery, and strict hygiene regulations.