Will Your Cement Imports into the EU Be Subject to CBAM in 2026?
Will Your Cement Imports into the EU Be Subject to CBAM in 2026?
“Will my cement imports into the EU be subject to CBAM in 2026?” For cement importers, construction-material distributors, and overseas suppliers, the answer depends on product classification, origin, import volumes, and applicable exemptions—not simply whether a shipment contains cement. As the EU’s Carbon Border Adjustment Mechanism enters its definitive phase in 2026, understanding your obligations is essential for assessing landed costs and supplier readiness.
The practical answer is usually yes if you import covered cement or clinker from a non-exempt origin and exceed the applicable annual mass threshold. But being within scope does not mean paying a flat carbon tariff at the border. The system involves importer authorization, embedded-emissions calculations, annual declarations, and the surrender of CBAM certificates.
Those distinctions matter when agreeing prices and delivery terms. A competitively priced shipment can become a difficult purchase if nobody has established who handles compliance or whether the producer can supply usable emissions records.
Start with the customs code, not the product description
CBAM coverage follows the Combined Nomenclature codes listed in Annex I of the EU CBAM Regulation. Commercial descriptions such as “construction binder,” “green cement,” or “cementitious material” cannot determine coverage on their own.
The principal cement and clinker classifications to check are:
Annex I also includes specified calcined clay under an “ex” classification. That qualifier matters: it means only the described portion of a customs heading is covered. Equally, concrete products are not automatically covered simply because cement was used to manufacture them. Review the classification of the imported goods themselves, using the current Annex I and customs guidance.
Origin and annual tonnage can change the answer
CBAM generally applies to covered goods originating in third countries, subject to the exclusions in the legislation. Annex III lists exempt countries and territories, including Iceland, Liechtenstein, Norway, and Switzerland. A preferential trade agreement with the EU does not, by itself, provide a CBAM exemption.
Use customs origin, not the supplier’s invoice address or the loading port. Cement routed through an exempt country does not become exempt merely through storage or transshipment. Where processing occurs in several countries, the applicable non-preferential origin rules need closer examination.
Under the amended rules, a 50-tonne annual mass threshold applies to the relevant mass-based CBAM goods. It is assessed per importer, cumulatively across the covered cement, iron and steel, aluminium, and fertiliser sectors—not separately for each shipment, supplier, or cement grade. Electricity and hydrogen are treated differently.
If the threshold is exceeded, obligations extend to the relevant imports for that calendar year, not just the tonnes above 50. A distributor expecting a small trial order should therefore consider later purchases and imports in other covered sectors before assuming an exemption will hold.
For ordinary bulk cement trade, this threshold is unlikely to be the decisive issue. It is more relevant to samples, occasional purchases, and small specialist consignments. Artificially splitting transactions to avoid obligations is not a sound compliance strategy.
What changes in 2026—and when certificates are due
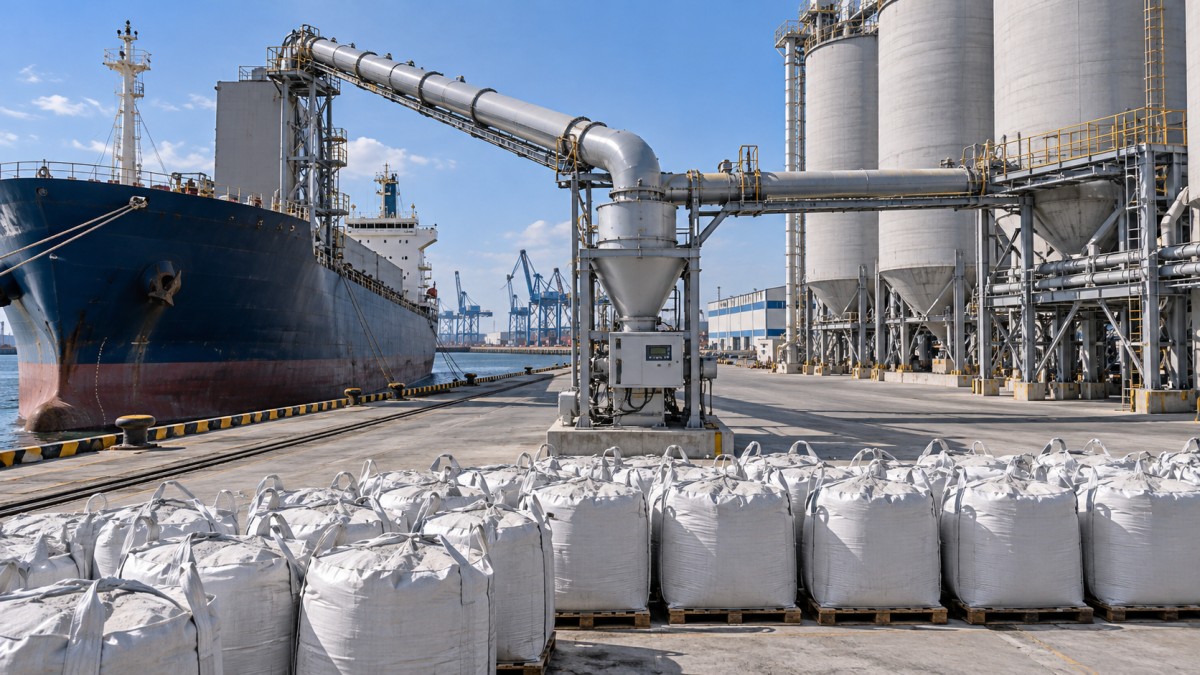
The transitional reporting period ended on 31 December 2025. Imports from 1 January 2026 fall under the definitive regime where applicable. Businesses should not assume that continuing their previous quarterly reporting process is sufficient.
For imports above the threshold, establish who must hold authorized CBAM declarant status. Depending on the arrangement, this may be the EU importer or an indirect customs representative. A freight forwarder handling customs entries is not automatically accepting responsibility for CBAM declarations and certificates.
There is also a critical difference between the year of import and the payment timetable. Under the amended framework, certificate sales for 2026 emissions begin in February 2027, and the first annual declaration and certificate surrender for 2026 imports are due by 30 September 2027. The later settlement date does not make 2026 imports free of financial exposure.
Finance teams should therefore assess the liability alongside purchasing commitments rather than wait for certificates to become available. Customs, procurement, and finance need the same import-volume records; otherwise, the emissions calculation may not reconcile with the quantities actually released for free circulation.
Ask the producer for emissions evidence, not a green label
Cement emissions are not simply a measure of electricity consumption. Clinker production releases carbon dioxide through limestone calcination as well as fuel combustion. For covered cement goods, the applicable calculation also includes indirect emissions associated with electricity, following the CBAM methodology.
This makes the production route important. A grinding plant purchasing clinker needs information about that precursor; its own electricity bill does not describe the full embedded-emissions position. A trader sourcing from several plants must also preserve the link between delivered material and the relevant production records.
Before approving a supplier, request:
- The producing installation’s identity and location, including the clinker source where relevant.
- The product category, reporting period, production quantities, and calculation methodology.
- Direct and indirect emissions information, with the allocation basis for the supplied goods.
- Supporting records for relevant precursors and electricity inputs.
- The verification arrangements for actual emissions and supporting evidence for any carbon price effectively paid.
An environmental product declaration can help assess a cement product, but it is not automatically a CBAM-compliant emissions submission. Its system boundaries, allocation methods, and treatment of transport or downstream stages may differ. Likewise, a corporate sustainability report rarely provides enough detail to calculate emissions for a particular installation and product.
Actual emissions used under the definitive regime require verification in accordance with the applicable rules. Where default values are permitted, use the official values and conditions—not a supplier’s unsupported industry average. Defaults can materially affect the commercial comparison, so model that possibility before signing.
Why the carbon cost is not a simple flat surcharge
A useful starting point is imported quantity multiplied by embedded emissions per tonne and the relevant certificate price. That is only a starting point. The final certificate requirement also reflects the adjustment for EU ETS free allocation and any eligible deduction for a carbon price effectively paid in the country of origin.
CBAM is phased in alongside the reduction of free allocation for EU producers. Do not treat that phase-in as a universal discount applied mechanically to every supplier’s total emissions: the prescribed adjustment methodology matters. Certificate pricing is linked to EU ETS allowance prices, with specific arrangements for 2026 imports.
A foreign carbon tax or emissions-trading payment may support a deduction, but only where the legal requirements and evidence are satisfied. Rebates and other compensation must be considered. Voluntary carbon offsets are not equivalent to an eligible carbon price payment.
For sourcing decisions, compare suppliers under at least two conditions: accepted actual emissions and an applicable default-value scenario. Keep verification, administration, freight, duties, and financing costs visible rather than hiding everything inside an unexplained “CBAM surcharge.”
Build compliance into the purchase agreement
The most avoidable commercial problem is receiving technically acceptable cement without the information needed to declare it. Contracts should set emissions-data deadlines early enough for checking and verification, rather than allowing documents to arrive after the annual reporting work has begun.
They should also address changes in the supplying plant, clinker source, and production route. Substitution may leave the strength specification unchanged while altering embedded emissions and the supporting evidence. Require notice before substitution, and define how corrections or missing records affect the commercial settlement.
Incoterms alone do not settle these questions. A delivery term allocating freight or import costs does not replace a clear agreement on the authorized declarant, data provision, verification expenses, and carbon-cost adjustments. Nor does CBAM compliance replace the product conformity and performance documentation needed for the intended construction application.
Make the scope decision before comparing quotations
A workable assessment begins with four records: the confirmed CN code, documented origin, the importer’s cumulative annual covered tonnage, and the supplying installation’s emissions-data position. Together, these establish whether CBAM applies and how reliable the cost estimate can be.
This is where trade intelligence becomes useful beyond tracking regulatory headlines. Global Trade Insights & Industry Network (GTIIN) connects regulatory developments with building-material sourcing, supplier transparency, freight conditions, and procurement risks. Those factors belong in the same purchasing assessment, not in separate reports that never reach the buying team.
For legal scope and deadlines, consult the current consolidated CBAM Regulation, particularly its annexes, and the European Commission’s CBAM guidance. Resolve uncertain classification, origin, or authorization questions with the relevant customs or competent authority before shipment. The strongest quotation is not necessarily the lowest ex-works price; it is the one whose compliance assumptions you can substantiate.
 Can you trust flexible packaging market intelligence forecasts?Can you trust flexible packaging market intelligence forecasts? Learn how to verify sources, challenge assumptions, and assess demand before making costly investment or sourcing decisions.
 When is supply chain disruption management consulting worth the cost?When is supply chain disruption management consulting worth the cost? Learn how to compare fees, avoidable losses, and recovery options to make a confident investment decision.
 How to use macroeconomic analysis to forecast industrial demandApply an industrial macro analysis methodology to forecast demand, interpret economic signals, and plan inventory and capacity. Discover practical steps for smarter business decisions.
 How to assess Singapore suppliers with global supply chain intelligenceExplore international supply chain intelligence Singapore buyers can use to verify suppliers, assess capabilities and delivery risks, and make confident sourcing decisions.
 Which macroeconomic indicators help forecast U.S. industrial demand?Explore industrial macro analysis USA decision-makers can use to forecast demand. Track new orders, inventories, and credit signals to sharpen procurement and capacity decisions.
 Can a food processing manufacturer meet your small-batch needs?Can a food processing manufacturer meet your small-batch needs? Discover how to assess minimum orders, costs, packaging, and safety to choose the right partner for your launch.
 How to verify sourcing intelligence data before selecting suppliersVerify sourcing intelligence data before choosing suppliers. Learn how to check company records, certifications, and capacity to reduce procurement risk and build a reliable shortlist.
 How to use supplier risk analysis to spot financial warning signsUse supplier risk analysis to spot cash flow pressure, debt risks, and delivery warning signs. Learn practical steps to reduce exposure and protect supply continuity.
 When dual sourcing makes sense in a sourcing strategy for manufacturersSourcing strategy for manufacturers: learn when dual sourcing strengthens supply continuity, reduces disruption risk, and protects production without adding unnecessary complexity.
 How bulk commodities pricing affects long-term supply contractsBulk commodities pricing shapes long-term supply contracts through index rules, freight, quality, volume, and currency risk. Explore strategies for resilient costs and supply security.
 Which global manufacturing trends by sector matter most for sourcing plans?Global manufacturing trends by sector: identify sourcing risks, supplier resilience, compliance demands, and cost drivers to build smarter, more reliable procurement plans.
 What industrial trade intelligence pricing should include before you subscribeIndustrial trade intelligence pricing explained: compare coverage, data quality, access rights, and workflow value before choosing a subscription that supports smarter trade decisions.
 How an industrial trade intelligence dashboard can identify new supplier marketsDiscover how an industrial trade intelligence dashboard helps identify new supplier markets by comparing capacity, landed cost, logistics resilience, and compliance risk.
 Which global market entry barriers should exporters assess first?Global market entry barriers exporters should assess first: tariffs, compliance, buyer qualification, logistics, and payment risk. Build a practical strategy for confident market entry.
 How trade data aggregation analytics can reveal emerging supplier marketsTrade data aggregation analytics reveals emerging supplier markets by connecting trade flows, capacity signals, logistics, and compliance insights for smarter sourcing decisions.
 When an export market analysis platform can validate demand in a new marketExport market analysis platform insights help validate new-market demand through buyer fit, regulations, logistics, competition, and profitable entry conditions.
 What is driving the beauty and personal care market in the USA?Beauty and personal care in USA is driven by targeted solutions, selective premiumization, digital discovery, clean-label trust, diverse needs, and compliance. Explore key growth opportunities.
 How trade flow monitoring reports reveal changing regional demandTrade flow monitoring reports reveal changing regional demand through import volumes, sourcing shifts, product mix, logistics signals, and regulatory trends. Explore actionable market insights.
 How international market intelligence for investors reduces market-entry riskInternational market intelligence for investors reduces market-entry risk by validating demand, regulations, logistics, and competition before capital is committed.
 How international sourcing intelligence helps identify supplier risk earlyInternational sourcing intelligence helps businesses spot supplier risks early, protect supply continuity, and make smarter global procurement decisions.
 How trade data aggregation analytics reveals emerging supplier marketsTrade data aggregation analytics reveals emerging supplier markets through export trends, input flows, logistics, and regulatory signals. Discover smarter sourcing insights.
Global Trade Insights & Industry
Our mission is to empower global exporters and importers with data-driven insights that foster strategic growth.
Search News
Popular Tags
Industry Overview
The global commercial kitchen equipment market is projected to reach $112 billion by 2027. Driven by urbanization, the rise of e-commerce food delivery, and strict hygiene regulations.