Some Solar Leaders Narrow Third-Quarter Losses as Supply-Demand Imbalance Persists
As of October 31, 2026, third-quarter reports from several listed photovoltaic companies point to narrower losses at some industry leaders, even as the sector's supply-demand imbalance persists. The information provided identifies no policy, regulatory or trade-rule change; it does, however, give manufacturers and buyers reason to review procurement and delivery assumptions without treating improved results at some companies as evidence of a sector-wide recovery.
Losses Narrow for Some, Widen Upstream
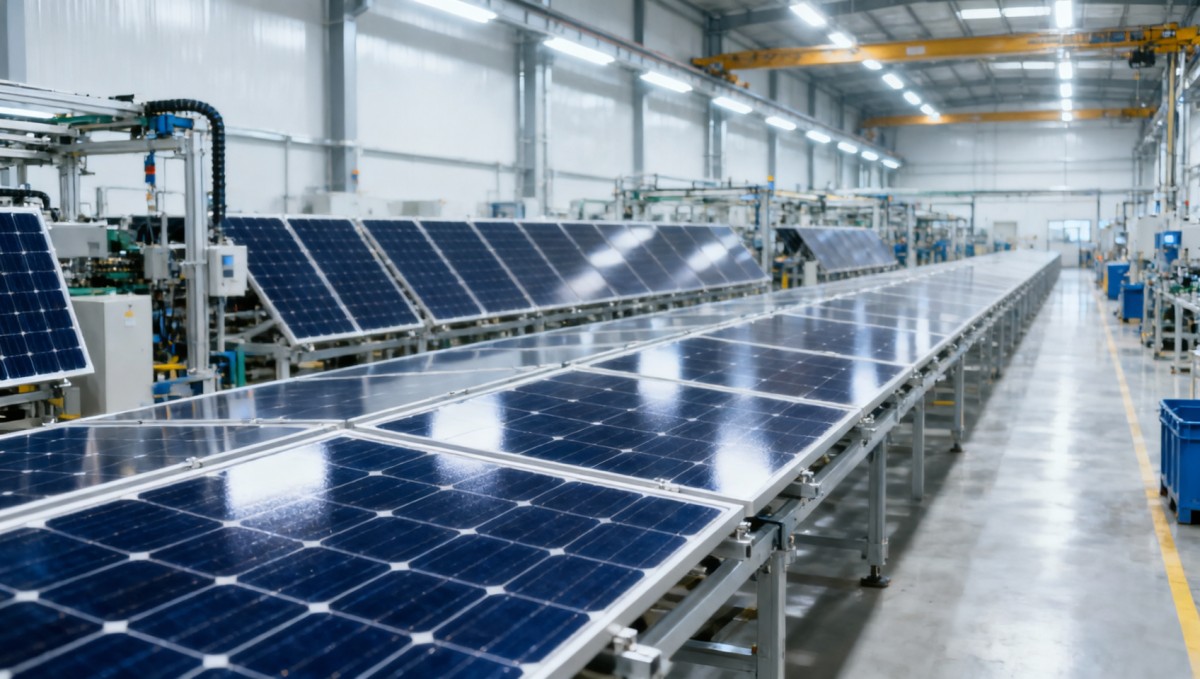
By October 31, 2026, several listed photovoltaic companies had released their third-quarter reports. In the third quarter, some leading companies significantly narrowed their losses through technology upgrades, adjustments to their product mix and contributions from energy-storage businesses. Upstream polysilicon producers continued to report widening losses. The overall supply-demand imbalance persisted, and the industry had not yet emerged from the bottom of its cycle.
Uneven Results Across the Supply Chain
Polysilicon Procurement and Manufacturing
From an industry perspective, widening losses among upstream polysilicon producers may prompt manufacturers to reassess supplier financial resilience and procurement planning. Buyers could review delivery schedules and supplier commitments, while recognizing that the reported losses alone do not establish whether any supplier's deliveries will be disrupted.
Product and Storage Purchases
Analysis suggests that changes in manufacturers' technology and product mix may make specification alignment more important for buyers and integrators. Where alternative photovoltaic or storage products are being considered, purchasers may need to verify technical documentation, applicable certifications and compatibility before changing an order. The information provided does not establish that any certification requirement has changed.
What to Check Before Committing to Orders
Review Supplier Commitments
Buyers may consider checking supplier qualifications, delivery commitments and contingency arrangements against their procurement plans. Financial results can inform that review, but they do not on their own establish a supplier's ability or inability to fulfill a particular contract.
Validate Product Changes
Where a proposed product differs from an earlier specification, purchasers and manufacturers can verify the relevant technical documents, test reports and applicable certifications. Any substitution should be assessed against the actual contract and project requirements rather than assumed to be acceptable.
Track Subsequent Rules and Tender Terms
Companies may also monitor policy announcements, certification guidance and tender documents for changes relevant to their business. No new rule or implementation detail is identified in the information provided, so any potential requirement would need separate verification.
Recovery Signals Need Further Evidence
In editorial assessment, the reports are better understood as evidence of uneven company performance within a continuing imbalance, not as the implementation of a new industry rule. Subsequent company results, industry feedback and any independently verified policy or procurement changes may help clarify whether the narrower losses signal a broader improvement.
A Measured Basis for Procurement Decisions
The reported improvement at some leading companies does not resolve the continuing pressure described upstream or establish that the industry has passed the bottom of its cycle. For now, the information is best used as a prompt to reassess supplier and product assumptions while monitoring further evidence.
Basis for This Report
This article is based on the user-provided news title, event date and summary. No specific official source link was provided in the input, so the underlying reports and any subsequent developments require continued verification. Relevant materials may include company announcements, official releases, industry association information and authoritative media reports. Further monitoring may cover industry feedback, company implementation and any verified changes to policy details, certification guidance, tender documents or trade execution.
 China Manufacturing PMI Falls to 49.3 in OctoberChina manufacturing PMI fell to 49.3 in October, signaling renewed contraction. Explore the role of weak export orders and domestic demand.
 Can you trust flexible packaging market intelligence forecasts?Can you trust flexible packaging market intelligence forecasts? Learn how to verify sources, challenge assumptions, and assess demand before making costly investment or sourcing decisions.
 When is supply chain disruption management consulting worth the cost?When is supply chain disruption management consulting worth the cost? Learn how to compare fees, avoidable losses, and recovery options to make a confident investment decision.
 How to use macroeconomic analysis to forecast industrial demandApply an industrial macro analysis methodology to forecast demand, interpret economic signals, and plan inventory and capacity. Discover practical steps for smarter business decisions.
 How to assess Singapore suppliers with global supply chain intelligenceExplore international supply chain intelligence Singapore buyers can use to verify suppliers, assess capabilities and delivery risks, and make confident sourcing decisions.
 Which macroeconomic indicators help forecast U.S. industrial demand?Explore industrial macro analysis USA decision-makers can use to forecast demand. Track new orders, inventories, and credit signals to sharpen procurement and capacity decisions.
 Can a food processing manufacturer meet your small-batch needs?Can a food processing manufacturer meet your small-batch needs? Discover how to assess minimum orders, costs, packaging, and safety to choose the right partner for your launch.
 How to verify sourcing intelligence data before selecting suppliersVerify sourcing intelligence data before choosing suppliers. Learn how to check company records, certifications, and capacity to reduce procurement risk and build a reliable shortlist.
 How to use supplier risk analysis to spot financial warning signsUse supplier risk analysis to spot cash flow pressure, debt risks, and delivery warning signs. Learn practical steps to reduce exposure and protect supply continuity.
 When dual sourcing makes sense in a sourcing strategy for manufacturersSourcing strategy for manufacturers: learn when dual sourcing strengthens supply continuity, reduces disruption risk, and protects production without adding unnecessary complexity.
 How bulk commodities pricing affects long-term supply contractsBulk commodities pricing shapes long-term supply contracts through index rules, freight, quality, volume, and currency risk. Explore strategies for resilient costs and supply security.
 Which global manufacturing trends by sector matter most for sourcing plans?Global manufacturing trends by sector: identify sourcing risks, supplier resilience, compliance demands, and cost drivers to build smarter, more reliable procurement plans.
 What industrial trade intelligence pricing should include before you subscribeIndustrial trade intelligence pricing explained: compare coverage, data quality, access rights, and workflow value before choosing a subscription that supports smarter trade decisions.
 How an industrial trade intelligence dashboard can identify new supplier marketsDiscover how an industrial trade intelligence dashboard helps identify new supplier markets by comparing capacity, landed cost, logistics resilience, and compliance risk.
 Which global market entry barriers should exporters assess first?Global market entry barriers exporters should assess first: tariffs, compliance, buyer qualification, logistics, and payment risk. Build a practical strategy for confident market entry.
 How trade data aggregation analytics can reveal emerging supplier marketsTrade data aggregation analytics reveals emerging supplier markets by connecting trade flows, capacity signals, logistics, and compliance insights for smarter sourcing decisions.
 When an export market analysis platform can validate demand in a new marketExport market analysis platform insights help validate new-market demand through buyer fit, regulations, logistics, competition, and profitable entry conditions.
 What is driving the beauty and personal care market in the USA?Beauty and personal care in USA is driven by targeted solutions, selective premiumization, digital discovery, clean-label trust, diverse needs, and compliance. Explore key growth opportunities.
 How trade flow monitoring reports reveal changing regional demandTrade flow monitoring reports reveal changing regional demand through import volumes, sourcing shifts, product mix, logistics signals, and regulatory trends. Explore actionable market insights.
 How international market intelligence for investors reduces market-entry riskInternational market intelligence for investors reduces market-entry risk by validating demand, regulations, logistics, and competition before capital is committed.
 How international sourcing intelligence helps identify supplier risk earlyInternational sourcing intelligence helps businesses spot supplier risks early, protect supply continuity, and make smarter global procurement decisions.
Global Trade Insights & Industry
Our mission is to empower global exporters and importers with data-driven insights that foster strategic growth.
Search News
Popular Tags
Industry Overview
The global commercial kitchen equipment market is projected to reach $112 billion by 2027. Driven by urbanization, the rise of e-commerce food delivery, and strict hygiene regulations.